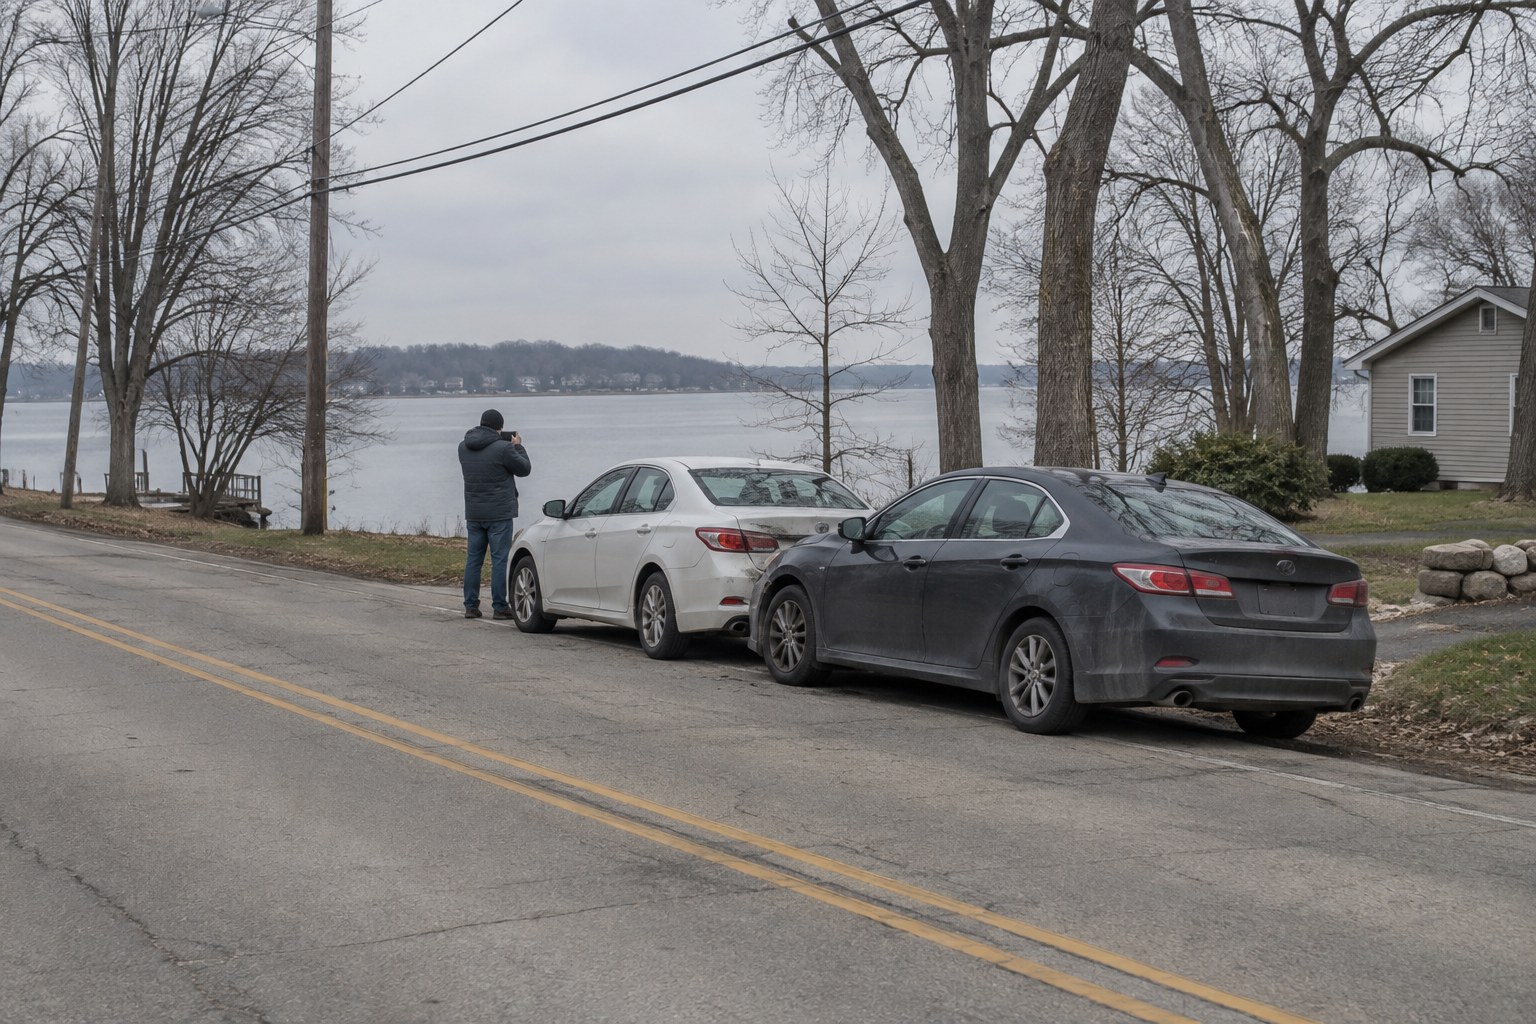
Knowing how to file an insurance claim before you ever need to is one of the most useful things you can do as a driver or homeowner. A fender bender on Route 12, a tree limb through the roof after a summer storm, or a basement that takes on water during a spring thaw can all leave you rattled and unsure where to start. As a family owned agency on Route 12 in Fox Lake, we work with multiple carriers and help our neighbors through claims every week. Here is the process, step by step, so you know what to do and what to keep track of when something goes wrong.
Dealing with a loss right now? Call us and we will help you figure out the next step.
Key Takeaways
- Your first priority after any accident or home loss is safety, for you, your passengers and your family, before photos or phone calls.
- Photos, a police report number and a written list of damage give your carrier the information it needs to review your claim.
- Most policies expect you to take reasonable steps to prevent further damage, like tarping a roof or shutting off water.
- Reporting promptly and keeping copies of every receipt, estimate and conversation helps the claim move along with fewer delays.
- Coverage, deductibles and claim procedures vary by carrier and policy, so review your own policy and ask your agent when something is unclear.
Step One Is Always Safety
It is tempting to grab your phone and start documenting right away. Wait until everyone is safe.
After a Car Accident
If you can, move your vehicle out of traffic to a shoulder or a nearby parking lot. On a busy stretch like Grand Avenue or Route 59, staying in a live lane can lead to a second collision. Turn on your hazard lights and check on everyone involved.
If anyone is hurt, or if you are unsure, call 911. Do not argue about who was at fault at the scene. Stick to exchanging names, phone numbers, insurance information, license plate numbers and vehicle descriptions.
After Damage at Home
For a fire, a gas smell or downed power lines, get out and call 911 or the utility first. For a burst pipe or storm damage, make sure the area is safe to enter. Standing water near outlets or a sagging ceiling are reasons to stay out until a professional checks it.
How to File an Insurance Claim for Your Car
Once everyone is safe, the auto claim process follows a fairly predictable path. The details depend on your carrier and the coverages on your auto insurance policy.
Get a Police Report When It Makes Sense
For crashes involving injuries or significant damage, police from Fox Lake, the Lake County Sheriff or the Illinois State Police will usually respond and write a report. Ask the officer for the report number and how to request a copy. Your carrier will often ask for it.
Illinois also has its own crash reporting rule. According to the Illinois State Police, each driver must file a crash report when a crash causes injury or death, or property damage over $1,500 ($500 if any driver involved is uninsured). If no police officer comes to the scene, the report should be filed with the Illinois State Police as soon as possible, within 10 days.
Take Photos Before Anything Moves
If it is safe, photograph both vehicles from several angles, the license plates, the road, traffic signs, skid marks and the weather conditions. A wide shot showing where the cars ended up can be as helpful as close ups of the dents. Write down the names and phone numbers of any witnesses.
Notify Your Carrier
Most carriers let you report a claim by phone, app or website, and many take reports around the clock. Have your policy number, the date, time and location, the other driver's information and the police report number ready. You can also call us and we will help you get the claim started.
Repairs, Rentals and the Appraisal
Your carrier may send an appraiser, ask you to use a photo estimate in its app, or have you visit a shop. Rental car coverage, towing and glass coverage are optional on many policies, so whether they apply depends on what you selected. If you have questions about what you carry, our post on how car insurance rates are determined explains how coverage choices fit together.
Filing a Home Insurance Claim Step by Step
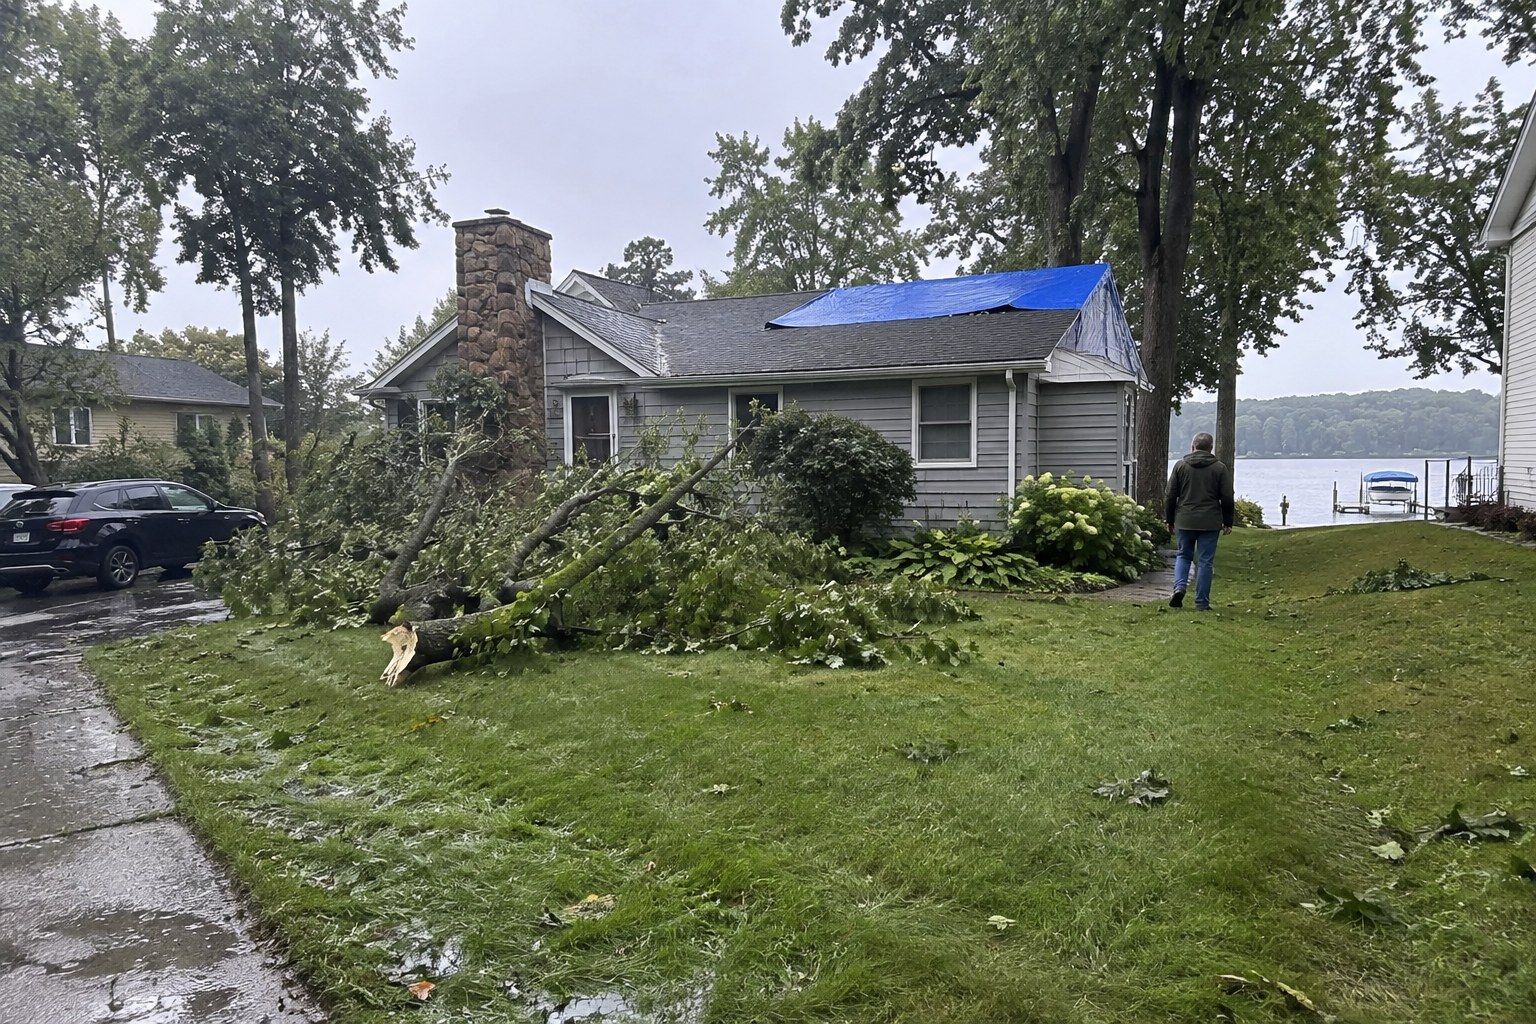
Home claims tend to involve more moving parts, especially when you need to keep living in the house while repairs are planned. Your home insurance coverage and its deductible will shape how the claim plays out.
Prevent Further Damage
Most homeowners policies expect you to take reasonable steps to protect your property from more damage after a loss. That might mean shutting off the main water valve, putting a tarp over a damaged roof, boarding a broken window or moving belongings out of a wet room.
Keep the receipts for supplies and any emergency services. Many policies consider reasonable temporary repair costs as part of the claim, though that varies by carrier and policy. Hold off on permanent repairs until your carrier has had a chance to see the damage, unless waiting would make things worse.
Document the Damage and Your Belongings
Photograph and video every damaged room before cleanup. Do not throw out damaged items until the carrier tells you it is okay, since an adjuster may want to see them. Make a list of damaged personal property with approximate age, cost and where you bought it.
A home inventory made before a loss makes this step much easier. A slow walk through each room with your phone camera, opening closets and drawers, can save hours of guessing later.
Report the Claim
Call your carrier or our office as soon as you reasonably can. Give a clear description of what happened and when. If you are not sure whether the damage is covered, ask. Water damage is a common example: a sudden burst pipe is often treated differently than gradual seepage or flood water, and flood is typically excluded from standard homeowners policies. Separate flood insurance is its own policy.
Not sure where your claim stands or what your policy says? Talk with someone who knows your account.
What to Expect From the Adjuster Visit
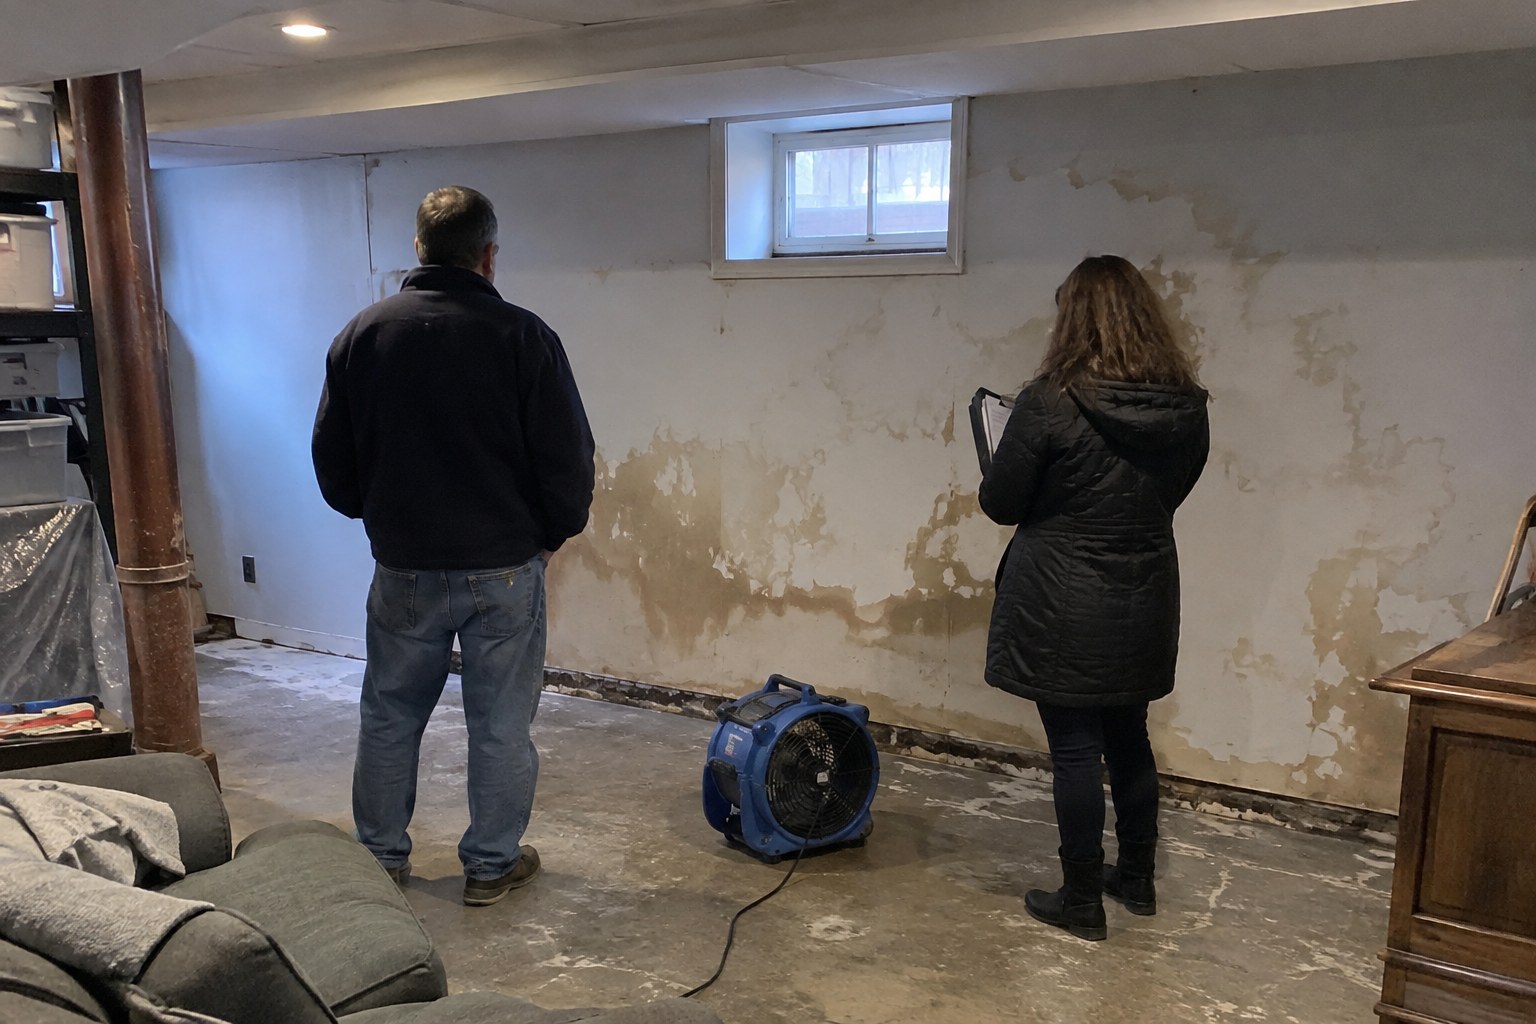
For many home claims and some auto claims, the carrier assigns an adjuster to inspect the damage and estimate the cost to repair or replace it.
Before the Visit
Gather your photos, your damage list, receipts for emergency repairs and any contractor estimates you already have. If you have older receipts or photos showing the condition of the roof, appliances or valuables before the loss, have those ready too.
During the Visit
Walk the adjuster through everything, including damage that is easy to miss, like water stains in a closet ceiling or a cracked foundation wall in the basement. Ask questions about how the estimate will be calculated, including whether your policy pays actual cash value or replacement cost. Our post on actual cash value vs replacement cost explains why that difference matters.
After the Visit
You should receive a written estimate. Read it line by line. If your contractor's estimate is higher or something is missing, you can ask the carrier to review it. Keep that conversation in writing when possible.
Documentation and Timelines to Keep Track Of
A claim can take days or months depending on the size of the loss. Good records keep things moving.
What to Keep
| Item | Auto Claim | Home Claim |
|---|---|---|
| Photos and video | Vehicles, plates, scene, road conditions | Every damaged room, before cleanup |
| Official reports | Police report number, SR 1 copy if filed | Fire or police report if applicable |
| Contact details | Other driver, witnesses, tow company | Contractors, restoration companies |
| Receipts | Towing, rental, medical bills | Tarps, emergency repairs, hotel stays |
| Claim log | Claim number, adjuster name, call dates | Claim number, adjuster name, call dates |
Illinois Claim Handling Timelines
Illinois regulates how carriers handle claims. Under the Illinois Administrative Code rules on improper claims practices (50 Ill. Adm. Code 919), insurers generally must acknowledge a claim within 15 working days and are expected to affirm or deny coverage within a reasonable time, providing written reasons if a claim is not resolved within 40 days of notice. The Illinois Department of Insurance takes consumer complaints if you believe a claim is being mishandled.
Your Own Deadlines
Policies usually require prompt notice of a loss and may set time limits for submitting proof of loss or filing suit. Those limits vary by carrier and policy, so check your declarations and policy language, or ask us to look with you.
How Our 24/7 Claims Support Helps
Losses do not wait for business hours. A deer on Route 173 at night or a sump pump failure during a weekend storm is exactly when you want a real answer.
Help Getting Started
Our team offers 24/7 claims support, so you can reach help to report a loss and understand your next step. We can connect you with your carrier's claims department and explain what information they will ask for.
Someone in Your Corner
Because we work with multiple carriers, we know how different claims departments operate. We cannot promise a claim outcome, since the carrier makes coverage decisions under your policy, but we can help you understand the process, follow up on stalled claims and answer questions along the way. We also offer service in English, Spanish and Romanian. Neighbors from Antioch to Grayslake and across Lake County rely on that support.
Reviewing Coverage After the Claim
A claim is often a good moment to check whether your limits and deductibles still fit your life. If a loss revealed a gap, we can compare options with you. Want help with a claim or a coverage review? Give our Fox Lake office a call.
Frequently Asked Questions
How soon should I report a claim?
As soon as you reasonably can after everyone is safe. Most policies require prompt notice of a loss, and waiting can make it harder to document what happened. Exact notice requirements vary by carrier and policy, so check your policy or call us at (847) 587-3200 if you are unsure.
Should I call my agent or the carrier first?
Either works. Many carriers take claim reports around the clock by phone or app. Calling our office first can help you confirm what information to gather and which coverages may apply, and we can help connect you with the right claims department. What matters most is reporting the loss promptly.
Do I need a police report for a minor accident?
Not always, but it often helps. A police report gives your carrier an independent account of the crash. In Illinois, if a crash causes injuries or property damage above the state thresholds and no officer comes to the scene, you may need to file a crash report with the Illinois State Police within 10 days. Check the current ISP rules for details.
Can I start repairs before the adjuster comes?
You should make reasonable temporary repairs to prevent further damage, like tarping a roof or stopping a leak, and keep the receipts. Permanent repairs are usually best held until the carrier has inspected or approved them. Take thorough photos first. Policies vary, so ask your carrier or agent before major work.
Will filing a claim raise my premium?
It might. Carriers consider claims history differently, and the effect can depend on the type of claim, who was at fault and your overall record. There is no single rule. If you are weighing whether to file a small claim, we can talk through the considerations with you.
What if I disagree with the settlement?
Start by asking the carrier to explain the estimate in writing and send any contractor estimates or documentation that support your position. Many policies include an appraisal process for disputes over the amount of loss. If you believe the claim was handled improperly, you can contact the Illinois Department of Insurance.
Learning how to file an insurance claim ahead of time means you can act calmly when a loss happens: stay safe, document everything, prevent further damage, report promptly and keep good records. If you have questions about a claim or your coverage, call Jablonski Insurance at (847) 587-3200 or stop by our office at 37 South St 12 Ste 2, Fox Lake, IL 60020.
Ready to Get Started with Jablonski Insurance?
Whether you are filing a claim today or want to make sure your coverage is ready for the next one, our family owned team is here to help. Call (847) 587-3200 to talk with a local agent.