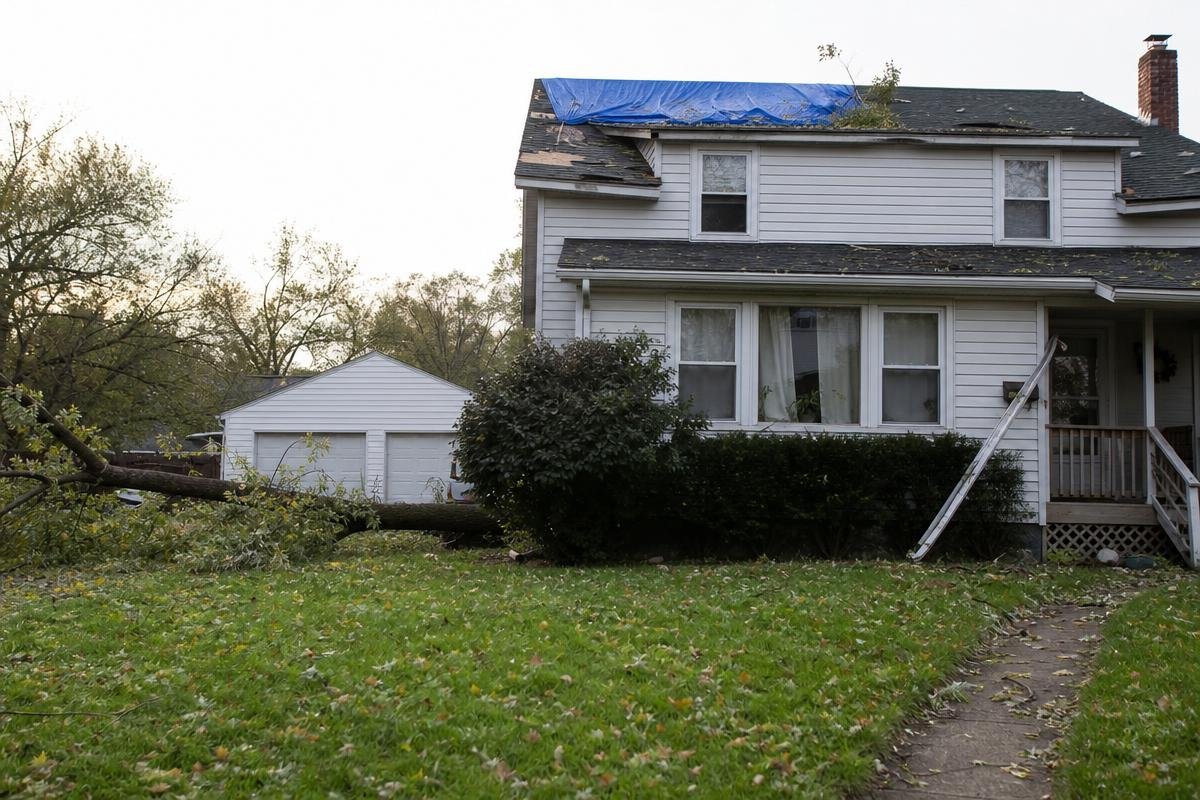
Living along the Chain O'Lakes means your home faces real exposure year-round. Spring snowmelt floods low-lying yards. Summer storms tear off shingles. Older homes can have roofing or plumbing conditions that make a small leak more consequential, depending on maintenance and the property’s condition. Most homeowners don't think about home insurance claims until something goes wrong, and that's exactly when gaps in coverage hurt the most. Jablonski Insurance is your local family owned agency, and we work from our office at 37 S Route 12, Ste 2, Fox Lake, IL 60020 helping Fox Lake homeowners understand what their policy actually covers before a claim ever happens.
Know what your policy covers before you need to use it. Talk to a local agent today.
Key Takeaways
- Wind, water damage, and theft are common types of homeowners insurance claims, depending on the property and circumstances.
- Standard homeowners insurance does not cover flood damage. Separate flood coverage is required for homes near the water.
- Documenting damage thoroughly before you file a claim directly affects how quickly and fully your insurer pays out.
- Older Fox Lake homes built before 1985 may face claim complications tied to outdated roofing, wiring, or plumbing.
- A local agent can review your policy and address coverage gaps before a loss occurs.
Why Do Fox Lake Homes Face Claims Other Illinois Homeowners Don't?
Homes in the Chain O'Lakes area carry risks that a house in Naperville or Springfield simply does not. The water is closer, the weather hits harder, and most standard policies were not written with lakefront living in mind.
Waterfront Exposure
Living near the water in northern Lake County means your home sits in a different risk category than most Illinois properties. Elevated humidity drives moisture into crawl spaces and wall cavities year-round. Water intrusion from the ground up looks a lot like flood damage, but your homeowners policy treats those two things very differently at claim time. That distinction can cost you thousands if you do not know it is going in.
Docks, seawalls, and detached structures near the shoreline often fall outside what a base homeowners policy covers. If a storm damages your dock or a neighbor's boat hits your seawall, you may need a separate rider to fill that hole in coverage. We serve homeowners across Lake and McHenry counties, including Antioch and Spring Grove, and lakefront owners throughout the region face this same issue.
If you carry boat and watercraft insurance in Fox Lake, ask us whether your dock and shoreline structures are covered under the same policy or need their own endorsement.
Seasonal Weather Patterns
The spring snowmelt in our area is a consistent claim driver. When the ground is still frozen and snowpack starts melting fast, water has nowhere to go except toward your foundation. Sump pump backup can create a significant claim. Coverage may require a specific endorsement, depending on the policy. Cost and coverage limits vary, so review the endorsement terms before relying on it.
A sump pump endorsement is one of the cheapest ways to protect against spring runoff. Ask us whether yours is in place.
Ice dams form when heat escapes through the roof, melts snow at the ridge, and refreezes at the eaves. Water backs up under shingles and into the attic. That is a covered loss under most homeowners policies, but many homeowners do not recognize it as one until the ceiling is already stained.
Spring and summer storms can cause hail and tree damage. The likelihood and severity depend on the weather event and the property.
What Are the Most Common Home Insurance Claims Filed by Fox Lake Homeowners?
Wind, water damage, fire, theft, and liability are the claim types local homeowners file most often. Knowing what your policy actually covers before damage happens is the difference between a straightforward claim and a denied one. Here is where the gaps tend to show up.
Wind and Hail
Wind and hail can cause significant property damage. Coverage for a particular loss depends on the policy terms, exclusions, and circumstances. The catch: many carriers apply cosmetic damage exclusions, and if your roof is over 15 years old, you may receive an actual cash value settlement rather than replacement cost. That means depreciation comes out of your payout before you see a dollar.
Aging roofing on pre-1985 construction is a real factor here. Know what settlement method your policy uses before a storm hits.
Does Homeowners Insurance Cover Water Damage and Frozen Pipes?
It depends on the source. Burst pipes and sudden internal water damage are covered under a standard policy, but gradual leaks are usually denied. Flooding and sump backup are not covered without separate riders, and while ice dam water intrusion is typically covered, the cost to remove the ice dam itself is not.
This is where homeowners get surprised most. The flood versus water damage distinction is covered in detail below under the coverage gap section, and it is the most misunderstood coverage issue we see in this area.
Fire and Smoke Damage
Fire and smoke damage is covered under virtually all standard homeowners policies. That includes smoke damage from a fire that started at a neighbor's house. Your policy responds to the damage at your property, not just fires you caused.
One local factor worth knowing: homes built before 1985 sometimes have knob-and-tube or aluminum wiring. That can affect both your claim outcome and your premium. If your home has older wiring, tell us before you file a claim. Older wiring can complicate a fire claim and raise your premium. Have us review your home's coverage before you need it.
Theft and Vandalism
Theft and vandalism are covered under most homeowners policies. But detached garages, lakeside sheds, and boat storage structures carry separate sub-limits, typically well below your main dwelling coverage. If you store equipment, tools, or watercraft gear in an outbuilding, check that sub-limit now. Most homeowners do not look until after a break-in.
If you rent out a property or host guests, a standard homeowners policy may not apply at all. Our coverage for rental properties page covers what that situation actually requires.
Liability Claims
Slip-and-fall accidents, dog bites, and dock accidents all fall under your liability coverage. Liability limits vary by policy. For waterfront homeowners, that can run out fast. If you have a dock, a boat, or regular guests on your property, ask us about umbrella coverage to address that exposure.
What Should You Do Immediately After Home Damage in Fox Lake?
Act fast to protect both your home and your claim. Storm damage, a burst pipe, or a tree through the roof, the first 30 minutes matter more than most homeowners realize. What you do right now affects whether your claim pays out fully, partially, or gets complicated. Here is exactly what to do.
Step 1: Prevent Additional Damage Right Now
Your policy may require reasonable steps to prevent additional damage. That is not optional language. Board up broken windows, tarp a damaged roof section, and shut off water at the main valve if a pipe has failed. Save every receipt for emergency materials and labor. Coverage for reasonable mitigation costs depends on the policy terms, so keep records of everything you spend.
Step 2: Document Everything Before You Touch It
Walk every affected room with your phone and shoot video before you move or discard anything. Photograph damage from multiple angles. Do not throw away damaged property until an adjuster has seen it or given you explicit permission. If you store a home inventory in a cloud backup, pull it up now. That list is the fastest way to produce a complete damaged-items record when you file a home insurance claim in Illinois.
Step 3: Call Your Local Agent Before You Call a 1-800 Number
Call us at (847) 587-3200 before you dial a national claims line. A local agent gives you a coverage check, a deductible-versus-claim-value conversation, and the right guidance before anything is formally filed. A claim inquiry or filed claim may affect future underwriting or available coverage options, depending on the insurer.
One quick call can prevent that. If you are dealing with water intrusion and are unsure whether your policy covers it, our flood coverage page explains the difference between flood and standard water damage coverage before you commit to opening a claim.
Step 4: Work With the Adjuster and Know Your Rights
After you file, the carrier assigns an adjuster. Claim timing varies by carrier, damage scope, documentation, and policy terms. If your home is uninhabitable, loss-of-use coverage pays for temporary housing, meals, and related costs while repairs happen. Homeowners across the region use this coverage more often than they expect after major storm events. You also have the right to dispute a settlement offer.
If the number looks short, call us. We can review the offer, explain what the policy language actually says, and push back on your behalf.
When Should You Actually File a Claim, and When Should You Not?
Filing a claim is not always the right move. That sounds strange coming from an insurance agency, but it is the honest answer. A quick call to us before you file can save you real money over the next three to five years.
The Deductible Math
Run the numbers first. Say a hailstorm hits a nearby home and causes $3,200 in roof damage. With a $2,500 deductible, your net payout is $700. A claim can affect future premiums and eligibility, depending on the carrier and claim history. Consider the deductible, expected payout, and potential long-term impact before filing a small claim.
The general rule: if the damage is less than twice your deductible, think hard before filing.
How Claims Affect Premiums in Illinois
Illinois does not prohibit carriers from surcharging after a first claim. Some carriers also remove claim-free discounts permanently after a single filed claim, not just temporarily. That discount can be worth more than the payout on a borderline loss.
There is also the CLUE report to consider. A filed claim can affect future underwriting and available coverage options. Ask your insurer how a claim may affect your specific policy.
Damage Types Worth Calling About Before Filing
There is a difference between reporting damage to your agent and formally filing a claim. Reporting does not automatically trigger a claim. It starts a conversation.
Call us first if you are dealing with any of these:
- Roof damage after a recent storm where the full scope is unclear
- Water damage of uncertain origin (covered pipe burst versus gradual leak)
- A liability incident where no formal demand has been made yet
We can help you figure out whether the damage is covered, whether the payout clears the deductible math, and whether filing makes sense before anything is officially on record. Not sure whether to file? Call us at (847) 587-3200 before you decide. A quick conversation now can protect your rates for years.
The Coverage Gap Fox Lake Homeowners Miss Most: Flood vs. Water Damage
Standard homeowners insurance never covers rising water. Full stop. If the lakes overflow onto your property, or spring runoff pushes water through your foundation, your policy will not pay for it. That is not a fine-print technicality. It is one of the most expensive surprises homeowners in our area face after a major storm.
What Your Policy Covers
Your standard policy covers water damage that starts inside the home. A burst pipe, a failed water heater, an appliance that leaks suddenly, those are covered losses. Water that enters from outside is not. Storm surge, overflowing lakes, and heavy rain runoff are all excluded under most standard policies.
Sump pump backup is also excluded by default. For homes near the water, that is a serious gap. Sump pump backup endorsement costs and limits vary by carrier and property. Review the available options before choosing coverage.
FEMA Flood Zones in Fox Lake
Properties in the Chain O'Lakes area fall in or near FEMA Special Flood Hazard Areas. If you carry a federally backed mortgage and your home sits in a high-risk zone, flood insurance is required by law. But many homes just outside the mapped boundary still flood regularly, and those owners carry no requirement and often no coverage at all.
You can look up your property's flood zone designation at msc.fema.gov. We can walk you through what the map actually means for your specific address. That is a quick conversation, not a full rewrite of your policy.
Adding Flood Coverage
Flood coverage is available through the National Flood Insurance Program or private carriers. Flood policies may have waiting periods and other eligibility conditions. Confirm the current terms before relying on coverage. If you are thinking about it, now is the right time to call.
Reach us at (847) 587-3200. We are at 37 S Route 12, Ste 2, Fox Lake, IL 60020 in Fox Lake, and we know this area's flood risk firsthand.
How Our Team Helps Fox Lake Homeowners Through a Claim
Filing a homeowners insurance claim is stressful enough without navigating a national call center that has never heard of Ingleside or Round Lake Beach. We can help you review your policy, understand the claims process, and communicate with your insurer while you work toward a resolution.
When a settlement offer seems low, we push back. A national 800 number reads from a script. We pick up the phone and make calls on your behalf. That is the difference between an agent who processes paperwork and one who actually advocates for you.
If you carry auto, home, or life coverage with us, one conversation can cover every open question at once. No repeating yourself to three different departments.
We Are Your Neighbors
Jablonski Insurance sits at 37 S Route 12, Ste 2, Fox Lake, IL 60020, right on the same corridor most of you drive every week. A real person answers at (847) 587-3200. We also serve homeowners in McHenry, Lake Villa, Ingleside, and across the region from this same office. Stop in or call. Either works.
Frequently Asked Questions
How do I file a home insurance claim in Fox Lake, IL?
Call us at (847) 587-3200 before you open a claim directly with your carrier. Document the damage with photos and video first. We can confirm what your policy covers, run the deductible math, and tell you whether filing actually makes sense before anything is on record.
Does home insurance cover water damage from Chain O'Lakes flooding?
Standard homeowners policies do not cover water that enters from outside, including lake overflow, storm surge, or rain runoff. A burst pipe or failed appliance is typically covered. External flooding requires a separate flood policy. If you are not sure which situation you have, call us and we will walk through it with you.
Will filing a home insurance claim raise my rates in Illinois?
A filed claim may affect future premiums, underwriting, or available coverage options, depending on the insurer and the claim history. That is exactly why calling before filing is worth the few minutes it takes. We can weigh the deductible math against a likely rate increase so you make the right call for your situation.
What is the home insurance claims process timeline?
Inspection and settlement timing vary by carrier, damage scope, documentation, and policy terms. Structural damage or disputed settlements can take longer. Keeping organized documentation from day one is the single biggest thing you can do to keep the process moving.
What should I document before calling my insurance agent after damage?
Photograph and video every affected area before moving or cleaning anything. List damaged items with estimated values and purchase dates where you can. Save every receipt for emergency mitigation work, like a tarp on the roof or water extraction. That paper trail protects your claim from the start.
How much does home insurance cost for Fox Lake homeowners?
Premiums vary based on home age, construction type, proximity to water, claims history, and coverage limits. Waterfront properties carry higher premiums than homes farther inland. Stop by our office at 37 S Route 12, Ste 2, Fox Lake, IL 60020 or call (847) 587-3200 for a clear quote with no surprises before you commit to a policy.
What home insurance coverage gaps do Fox Lake homeowners most often discover at claim time?
Three surprises come up again and again. Flood damage is not covered under a standard policy. Sump pump backup requires a separate endorsement. Detached structures like garages and sheds carry sub-limits that may not cover a full rebuild. Our home insurance in Fox Lake page covers these gaps in detail, and we can review your current policy to address the ones that matter most.
Home damage does not wait for a convenient time, and neither should your coverage review. If you are unsure what your policy covers, or you want to close a gap before the next storm season, call our team at (847) 587-3200. A real person answers. We can walk through your policy, run the deductible math on a potential claim, or help you add flood or sump pump coverage before you need it. One conversation is all it takes.
Ready to Get Started with Jablonski Insurance?
Call (847) 587-3200 to speak with our team directly. We're ready to answer your questions, walk you through your options, and help you find the right solution for your needs. Whether you're just starting to plan or ready to move forward, we'll make the process simple and stress-free. Reach out today and let's talk about how we can help.